How Much Money Do You Need for a Comfortable Retirement Life?

When I was younger, the only retirement numbers I heard were big, round, and honestly a bit terrifying. “You’ll need at least a million.” “Two million if you want to be comfortable.” Most of us just nod, change the subject, and go back to work. But somewhere between my first grey hair and my last career change, I realized I couldn’t dodge the question anymore: how much money do I actually need for a retirement that feels comfortable, not cramped — but also not wasteful?
This post is part of the same conversation I started in my last piece about the real emotional and practical side of retirement — the part you don’t see in glossy brochures. Think of this as the next chapter in that series: less theory, more numbers, and a grounded look at what “enough” can mean if you care about simplicity, not status.
1. The question everyone asks but nobody answers honestly
Whenever money comes up with friends around my age, someone eventually asks, “So… how much do you think we actually need to retire?” And then the room either fills with nervous jokes or someone quotes a number they saw on a U.S. finance blog that doesn’t really fit a Canadian life.
The honest answer is uncomfortable because it forces us to look at our choices. Not just our income, but our housing, our car habits, our grocery cart, our idea of fun. It also forces us to admit that some of the “standard” retirement advice was written for people with much higher salaries, bigger inheritances, and a taste for more expensive lifestyles than many of us actually want.
On Jay’s Playbook, I care more about intentional living than chasing some financial ideal. So let me be clear: you probably don’t need to be rich to retire comfortably in Canada. But you do need to be honest — painfully honest — about what “comfortable” means for you.
2. What “comfortable” actually means (it’s different for everyone)
When people say they want a “comfortable retirement,” they rarely define it. For some, comfort means winters in Mexico and a cottage in the summer. For others, it’s a small apartment, morning coffee, a library card, and enough health to walk to the park.
Here’s what “comfortable” looks like to me, and to many people who lean toward minimalism:
- A safe, clean place to live — not huge, but warm, quiet, and stable.
- Healthy, basic food without obsessing over every flyer and coupon.
- Being able to say yes to a coffee out, a simple dinner with friends, or a day trip now and then.
- Money set aside for prescriptions, dental work, glasses, and the other “little” health things that aren’t really little.
- Simple comforts at home: a good chair, a decent mattress, reliable internet, and a phone that works.
- Some buffer so that if the fridge dies or the car needs repairs, life is annoying but not catastrophic.
Notice what’s not on that list: luxury cars, designer kitchens, cruises every year. If those things genuinely matter to you, that’s your call — but they will dramatically change your retirement number.
So before we talk dollars, take a minute and picture your own comfortable day in retirement. Where are you living? How are you spending your time? Who are you with? Your number starts there, not in a calculator.
3. The basic numbers: a realistic monthly budget for a modest, comfortable life in Canada
Let’s talk numbers, but keep them grounded. I’m going to use a simple example: a single person living in a mid-sized Canadian city, renting a modest one-bedroom or studio, no dependents, no major debts, living a simple, not lavish, life.
| Category | Estimated Monthly Cost (CAD) | Notes |
|---|---|---|
| Housing (rent, utilities) | $1,400 – $1,900 | Modest apartment, heat/hydro included or partly included |
| Food & household basics | $450 – $650 | Cooking at home, limited dining out |
| Health (insurance, meds, dental) | $150 – $300 | Varies a lot; assumes some out-of-pocket costs |
| Transport | $120 – $450 | Transit pass on the low end; older, paid-off car on the higher end |
| Phone & internet | $120 – $180 | Canada isn’t cheap here; this is realistic |
| Leisure & personal spending | $200 – $400 | Cafés, small trips, hobbies, clothing |
| Miscellaneous & replacement | $150 – $250 | Appliances, gifts, small emergencies |
| Approximate total | $2,590 – $4,130 | Round to a simple planning number that fits your reality |
If you average those ranges, you’re looking at something like $3,200 – $3,500 a month for a modest but comfortable life in many parts of Canada. Big cities like Toronto or Vancouver can easily push the housing line much higher, while smaller towns might lower it.
Remember, this is a starting point, not a verdict. Your own budget might be lower if you:
- Own your home outright and only pay taxes, condo fees, and maintenance.
- Share housing with a partner or roommate.
- Use transit, walk, or bike instead of owning a car.
- Already live simply and don’t need to make big lifestyle cuts.
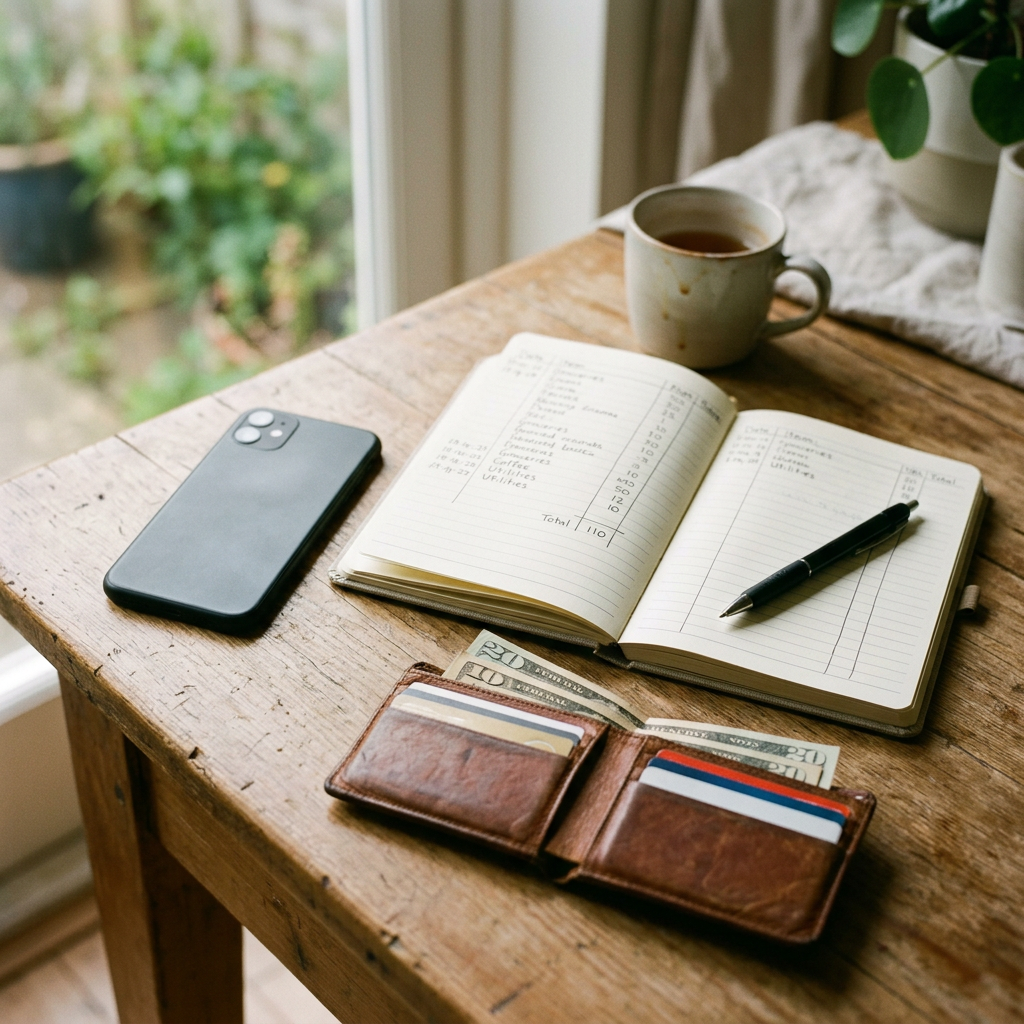
Or higher if you have ongoing health issues, support family members, or just genuinely value certain “extras.” The key is that you stop guessing and start writing down real numbers.
4. The myth of the “magic number” — why $1M isn’t what you think
You’ve probably seen the headline: “You need $1 million to retire.” It sounds precise. Scientific, almost. The problem is, it’s usually just a rough rule based on assumptions that may not match your life — or the Canadian reality of taxes, housing, and healthcare.
Here’s a very simple way people back into that number: they assume you can safely spend around 4% of your invested money per year without running out too early. Four percent of $1,000,000 is $40,000 a year, or about $3,333 a month before tax.
Now compare that to the sample budget above. For some people, that $40,000, plus Canada Pension Plan (CPP) and Old Age Security (OAS), might be more than enough. For others, especially in high-cost cities or with higher expectations, it won’t feel like nearly enough.
And on the flip side, if you live simply in a paid-off home in a smaller community, your personal “enough” might be far below $1 million, especially once you factor in CPP, OAS, and any workplace pensions.
The magic-number mindset is dangerous because it:
- Panics people into thinking they’re doomed if they don’t hit a big, round target.
- Tempts others to quit as soon as they hit that target, even if they haven’t tested their actual spending.
- Ignores how powerful thoughtful, minimalist choices can be in bringing that target down.
Instead of asking, “How do I get to $1 million?” a better question is, “How do I build a life where my real, honest expenses are friendly to the savings and income I can realistically create?”
5. How spending less doesn’t mean living less — the minimalist retirement mindset
In my earlier article on retirement reality, I wrote about how much of our working life is built around buying back time we don’t even have. Retirement gives you something you haven’t had in years: space. And space, used intentionally, can make a “smaller” retirement budget feel surprisingly big.
A minimalist retirement isn’t about deprivation. It’s about cutting the parts of your spending that don’t actually make your days better. Some examples:
- Cooking most meals at home, but really enjoying them — slow breakfasts, simple soups, baking bread.
- Trading expensive trips for longer, slower stays with friends or family, or local adventures you never had time for before.
- Owning fewer, better things — one pair of shoes you love and wear, instead of five you forget.
- Leaning on public libraries, community centres, and parks instead of paid entertainment.
- Right-sizing your home so you’re not heating, furnishing, and insuring rooms you never use.
When your days are less rushed, you have more room for things that don’t cost much: walking, reading, talking, tinkering, volunteering. That’s the real trade-off minimalism offers — not just less spending, but a different shape to your days.
From a numbers perspective, every $100 you don’t need to spend each month lowers the amount you need saved to support that lifestyle. Over a year, that’s $1,200 less you have to pull from savings or pensions. Multiply that over 20 or 30 years, and “small” choices become very big levers.
6. A practical framework: how to estimate your number
Let’s pull this together into something you can actually use. This is the same framework I’ve been using in my own planning — it’s simple, imperfect, and honest.
- Design your ordinary day. Write down what a normal Tuesday in retirement looks like for you. Not a dream vacation — a regular day. Where do you live? What do you do for fun? How often do you eat out? This helps you anchor your budget in reality.
- Build a bare-bones monthly budget, then add comfort. Start with the categories above: housing, food, health, transport, phone/internet, leisure, misc. Write down real numbers for your situation, not mine. Then add a “comfort” buffer of 10–20% so you’re not budgeting for your absolute minimum.
- Factor in Canadian benefits and pensions. Look up your estimated CPP, any workplace pensions, and what you might get from Old Age Security. These aren’t exact, but they’ll give you a ballpark of your future monthly income that doesn’t have to come from savings.
- Calculate how much your savings need to cover. Take your monthly budget, subtract your expected CPP/OAS/pensions, and see what’s left. Multiply that gap by 12 to get the yearly amount your savings need to provide.
- Rough in a savings target. As a very simple rule of thumb, take that yearly gap and multiply it by somewhere between 20 and 25. That’s based on the idea that you might be able to sustainably draw 3–5% a year from your investments over the long term. It’s not a guarantee, but it’s a useful planning anchor.
- Stress-test the plan. Ask yourself: what if rent goes up more than I expect? What if I live longer than I think? What if I need more health care? This is where you might increase your target a bit or adjust your expectations about work, part-time income, or location.
- Look for levers, not miracles. Instead of trying to conjure an extra $500,000, look for ways to shrink your required monthly spending in a way that still feels like living. Could you move to a smaller place? Share a car? Delay big purchases? Those choices may matter more than an extra bump in investment returns.
This isn’t as flashy as a magic “You need $X” answer. But it’s tailored to your real life. And that’s the only life you’re going to retire into.
7. Closing: choosing peace of mind over perfection
If you came here looking for a single number, I know this might feel a bit unsatisfying. But here’s what I’ve learned, both from my own path and from countless conversations with people nearing retirement: peace of mind doesn’t come from hitting someone else’s target. It comes from knowing your own numbers, your own priorities, and your own trade-offs.
You don’t need a perfect plan. You need a believable one. One that’s honest about where you are, clear about what “comfortable” means to you, and flexible enough to adjust as life happens.
In this ongoing retirement series on Jay’s Playbook, I’ll be digging deeper into some of these pieces — including practical ways to lower your housing costs without feeling squeezed, how to think about part-time work in retirement, and simple systems for tracking your spending without turning your life into a spreadsheet. If you’re willing to keep asking honest questions, I’ll keep sharing what I learn.
For now, your homework is simple: grab a notebook, write down what a comfortable day looks like for you, and start sketching the real costs of that life in Canadian dollars. That’s where your true retirement number begins — not in fear, not in fantasy, but in the quiet, ordinary details of a life you actually want to live.